M&A and Fundraising Analysis for November 10, 2026
Defense, pharma, and banking drive today's structuring moves — while niche consolidation (specialty insurance, independent music, hygiene services) shapes tomorrow's players, sector by sector.
· Proplace
🌡️ Sectors on the move — hover a sector to see its deals, click to open it
Open this edition in the cockpit →Every deal of the day, unfolded, evaluable in one click.
The day is marked by two distinct regimes: on one side, large-scale operations that reconfigure entire sectors — a record European pharmaceutical LBO, a Franco-Italian banking merger, a defense platform raising at a billion-dollar valuation nine months after its creation; on the other, a series of niche consolidations where regional or specialized operators acquire competitors to densify their networks. Between these two registers, a common logic: capital seeks assets whose value relies on positions difficult to replicate — artist catalogs, aquaculture licenses, local networks, seed patents.
🤝Signed-deals stream · 1111 in the edition · 10 evaluable in the cockpit
- Recordati
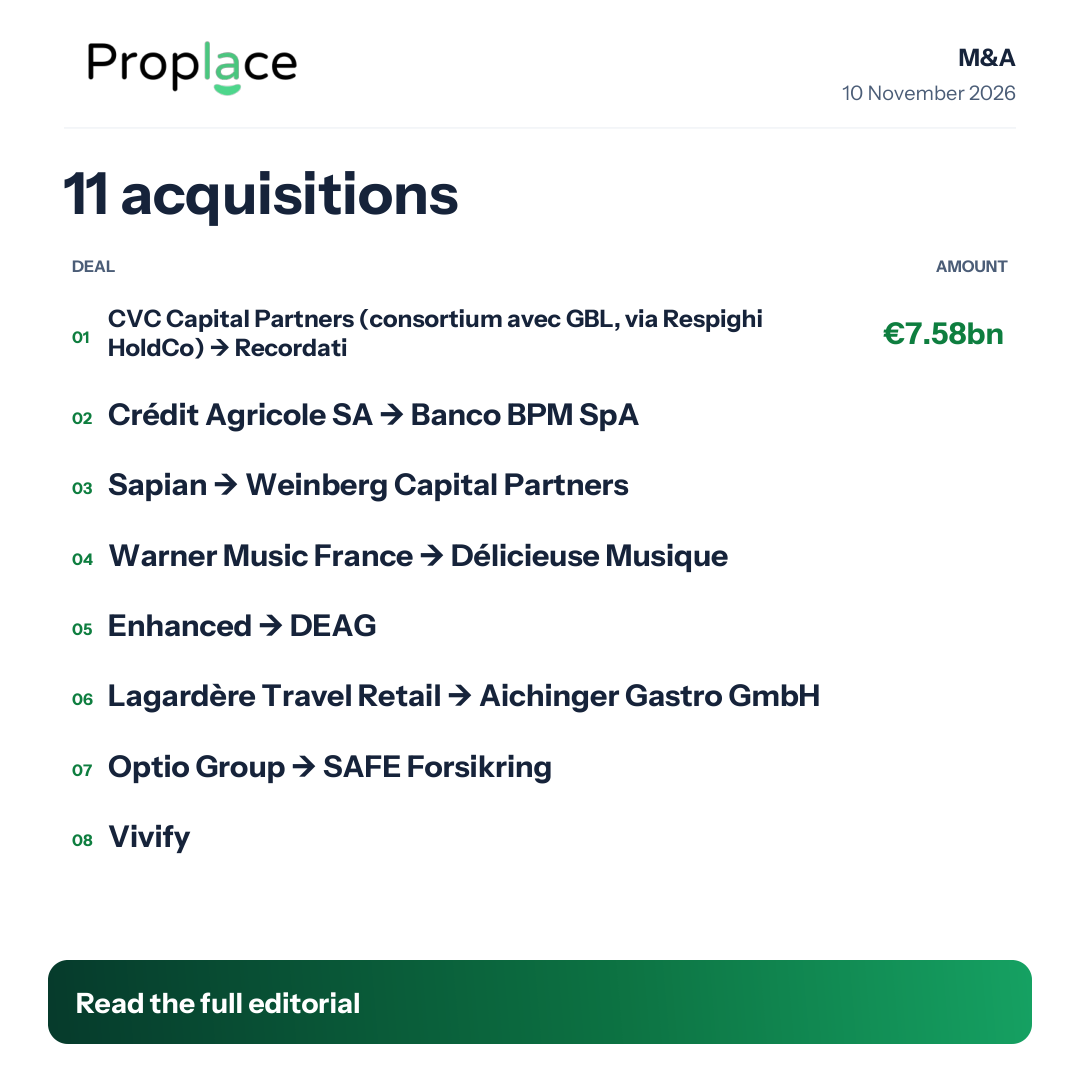
CVC acquires Recordati: Europe's largest LBO of 2026, financed without a dominant bank
- Banco BPM SpApymnts.com
Crédit Agricole — Banco BPM: Italy's third-largest bank takes shape from Paris
- Weinberg Capital Partnerslagazettefrance.fr
Sapian acquires Aérolia, Servitec, and EC Assainissement: three acquisitions, one territorial network
- Délicieuse Musique
Warner Music France absorbs Délicieuse Musique: Bordeaux electronic catalog joins the major
Warner Music France absorbs Délicieuse Musique: Bordeaux electronic catalog joins the major
Source: musicbusinessworldwide.com → · Sector Media & Entertainment — 📬 subscribe to the Media & Entertainment newsletter
Délicieuse Musique is a group of independent labels founded in 2012 in Bordeaux by Mathieu Léglise and Gautier de Bosredon. It manages ten imprints — including Délicieuse Records, Nice Guys, Noire & Blanche, Egoplanet — and represents over 1,200 artists in electronic genres (chill, lounge, deep house, jazz house) and indie pop. Its past signings include Lost Frequencies, Ofenbach, Bakermat, and Kungs.
Warner Music France acquires 100% of Délicieuse Musique. Financial terms are not disclosed. The company will continue to operate autonomously from Bordeaux, under the direction of its co-founders. The associated publishing house, GLM Editions, remains independent. The operation is described by Warner Music France as the first step in a strategy of partnerships with the French independent sector.
Strategic interpretation: Warner is not acquiring Délicieuse for its current revenues — it is acquiring its talent identification pipeline. An independent Bordeaux label that signed Lost Frequencies and Ofenbach before their international breakthrough possesses something that streaming algorithms cannot replicate: a trusted network with emerging artists who would refuse to sign directly with a major. By acquiring the independent wrapper while attaching WMG's global distribution and synchronization resources, Warner gains access to this pipeline without destroying it — provided it keeps its promise of autonomy.
- DEAG
Enhanced acquires DEAG: a bet on the experience economy, financed by shares
Enhanced acquires DEAG: a bet on the experience economy, financed by shares
Enhanced, a US group listed in New York, known for the Enhanced Games — a sports competition where doping is allowed. Christian Angermayer, co-founder of Enhanced, controls both Enhanced and is among the sellers of DEAG.
The structure deserves careful reading: an acquirer whose market capitalization was lower than the imputed value of the target pays in newly issued shares, in an operation where the main seller is also a co-founder of the acquirer. The operation is presented as a "merger" — which is accurate in terms of the people involved. For DEAG's minority shareholders, the question is whether the €4 per share premium reflects the value of a festival network generating hundreds of millions of euros in revenue, or if it is constrained by Enhanced's limited financing capacity.
- Aichinger Gastro GmbHtageskarte.io
Lagardère Travel Retail enters Munich: the tenth German airport
- SAFE Forsikringinsurancebusinessmag.com
Optio and Taurus: two British specialists densify their European presence
- A. Ruckstuhl Elektrotech
Ruckstuhl Elektrotech joins A. Lehmann Elektro: building technology expansion towards Zurich
- RG Groep's commercial vehicle businessautomotive-online.nl
TTG Truck en Trailer acquires RG Groep's commercial vehicle activities
- De Waagh
Heuf Horeca acquires De Waagh in Nijmegen: fifth establishment for a local consolidator
Heuf Horeca acquires De Waagh in Nijmegen: fifth establishment for a local consolidator
Heuf Horeca, a Dutch catering company founded by Marcel van den Heuvel (38), operates four establishments in Nijmegen: the party bars Tappers and Bar Ruig, the Steven restaurant, and Brasserie Jan. The current owner will retain a minority stake and an operational role in the background.
Local consolidation operation: Van den Heuvel explicitly cites economies of scale (purchasing, personnel management) as a growth driver, in a sector where margins remain under pressure.
Crédit Agricole — Banco BPM: Italy's third-largest bank takes shape from Paris
Source: pymnts.com → · Sector FinTech — 📬 subscribe to the FinTech newsletter
Crédit Agricole SA proposes to merge its Italian banking operations — grouped under Crédit Agricole Italia — with Banco BPM SpA, in which it already holds a 29.6% stake.
The proposed terms include an exchange ratio incorporating a 20% premium on Banco BPM's valuation, along with an extraordinary dividend of €1 billion paid to Banco BPM shareholders. Crédit Agricole estimates annual pre-tax synergies at approximately €800 million and projects an increase of around 24% in Banco BPM's earnings per share from 2027. Crédit Agricole's stake in the combined entity would rise to approximately 45%. Banco BPM would retain its listing in Milan, its Italian identity, and its CEO Giuseppe Castagna.
Strategic interpretation: Crédit Agricole cannot become number one in France — its mutualist model structurally prevents it. Italy has been its priority expansion territory for several years. By increasing its stake from 29.6% to 45% in a combined entity. The market reaction — Banco BPM up more than 9%, Crédit Agricole slightly down — reflects exactly this asymmetry: the target's shareholders capture the premium, while the acquirer's shareholders question the price of external growth.
Sapian acquires Aérolia, Servitec, and EC Assainissement: three acquisitions, one territorial network
Sapian is a French group providing building hygiene services and protection of living spaces, founded 45 years ago and acquired from ISS by Weinberg Capital Partners in 2019. It operates in four business lines: air hygiene, pest control, sanitation, and fire protection. It has over 1,500 employees and forty agencies serving approximately 48,000 clients.
Sapian announces three simultaneous acquisitions: Aérolia (Radinghem-en-Weppes, Nord), specializing in air hygiene, industrial cleaning, and disinfection for industry, healthcare, agri-food, and local authorities; Servitec (South-West), specializing in air hygiene and fire protection; EC Assainissement (Ain), a historical player in wastewater purification and treatment. The combined revenue of the three targets exceeds €10 million.
The logic is that of a regional consolidator in an acceleration phase: each acquisition densifies a business in a geography, without changing the model. The next external growth operation dated back to 2024; by making three simultaneous acquisitions, Sapian signals that it is entering a more active phase — which, for a seller of technical services SMEs in France, deserves attention.
Lagardère Travel Retail enters Munich: the tenth German airport
Source: tageskarte.io → · Sector Mobility & Transportation — 📬 subscribe to the Mobility & Transportation newsletter
Lagardère Travel Retail operates retail and catering outlets in airports. Before this operation, it was present in nine German airports with over 200 points of sale. Aichinger Gastro GmbH, founded in 2003 and managed by Elena and Markus Aichinger, operates six catering outlets in the secured area of Munich Airport, offering coffee specialties and Asian cuisine concepts.
Lagardère Travel Retail acquires Aichinger Gastro, extending its presence to ten German airports. Existing concepts will be maintained. Markus Aichinger will remain involved in an advisory role.
A geographical consolidation operation with no particular surprise: Munich is Germany's second-largest airport by traffic, and its absence from the Lagardère network was a visible gap. The real value of this type of acquisition is not in the target's revenue but in the airport concessions it holds — regulated positions that are difficult to obtain other than by acquiring an existing operator.
Optio and Taurus: two British specialists densify their European presence
Source: insurancebusinessmag.com → · Sector InsurTech — 📬 subscribe to the InsurTech newsletter
Optio Group is a specialized insurance group. It acquires SAFE Forsikring, a Norwegian MGA (managing general agent) founded in 2012, specializing in underwriting aquaculture, offshore energy, and marine risks via underwriting delegations. SAFE will be integrated into Optio's Norwegian platform alongside S Insurance and AGS Forsikring, under the continued leadership of its founder Thore Amundsen.
Taurus Insurance Services, a Gibraltar-based lifestyle insurance specialist (gadgets, travel), acquires Status Insurance Management, a British and Cypriot operator holding Lloyd's capacity, which distributes via brokers, financial advisors, travel agencies, and affiliated partners. Status operates notably under the brand Europesure (travel insurance for British and European residents), and also offers international medical and student insurance.
Both operations reflect the same dynamic: MGAs and niche specialists are preferred targets for consolidation in European insurance distribution, as they combine difficult-to-replicate risk portfolios and established distribution channels.
Vivify acquires imin: connecting school sports facilities to booking platforms
Source: businesscloud.co.uk → · Sector Media & Entertainment — 📬 subscribe to the Media & Entertainment newsletter
Vivify, a Manchester-based technology company, helps over 6,000 UK schools open their sports facilities (halls, pitches) to local communities outside school hours, founded in 2020. imin, based in London and founded in 2014, co-created OpenActive, the open data standard for physical activities supported by Sport England. Its technology allows users to discover and book sports activities by aggregating information available on different platforms (Decathlon, LTA Play, Every Body Moves by ParalympicsGB).
Vivify acquires imin for undisclosed terms. The combined entity will offer five solutions: slot management and instant payment, intelligent planning, marketplace, data analytics, and school facility management.
Strategic interpretation: Vivify owns the physical infrastructure (agreements with schools); imin owns the digital distribution layer (data feeds and integrations with booking platforms). The acquisition is a classic vertical integration: without imin, Vivify remains a slot manager; with imin, it becomes an entry point for anyone seeking an accessible sports activity in their community — which fundamentally changes the value proposition for local authorities and leisure operators.
Ruckstuhl Elektrotech joins A. Lehmann Elektro: building technology expansion towards Zurich
A. Ruckstuhl (55 employees) brings ICT (information and communication technologies) and energy technology expertise that Lehmann did not cover. The combined entity has 240 employees. Ruckstuhl will continue to operate autonomously under its current management.
Regional consolidation in a fragmented sector, with a clear logic: geographical densification towards the Zurich economic basin and expansion of the service offering.
TTG Truck en Trailer acquires RG Groep's commercial vehicle activities
Source: automotive-online.nl → · Sector Mobility & Transportation — 📬 subscribe to the Mobility & Transportation newsletter
TTG Truck en Trailer, a subsidiary of the Dutch Wensink Groep, has acquired the commercial vehicle activities of RG Groep. Financial details and the precise scope of the acquired activities are not disclosed in available sources.
💰Fresh-funding radar · 00 evaluable in the cockpit
CVC acquires Recordati: Europe's largest LBO of 2026, financed without a dominant bank
Source: investorsinhealthcare.com →
Recordati is an Italian pharmaceutical group listed on Euronext Milan, specializing in rare diseases and specialty medicines. CVC Capital Partners, leading a consortium including GBL, is launching a public tender offer to delist all Recordati shares, structured via the holding company Respighi HoldCo.
The secured financing totals €7.58 billion, making it the largest LBO announced in Europe in 2026. The architecture is unusual in its size and composition: approximately €6.05 billion in senior secured debt in fixed and variable rate bonds, split into five tranches (including two denominated in dollars), an €850 million revolving credit facility, and a €1.53 billion PIK tranche issued by a separate entity (Respighi Investments). Twenty-four banks acted as initial underwriters. The first settlement of the offer took place on November 2; the second is scheduled for November 17.
The obvious interpretation: CVC is betting on the resilience of rare disease revenues, whose regulatory barriers and administered prices protect margins, to justify massive leverage.
What deserves attention is the structure itself: the absence of a classic bank term loan at the core of the arrangement — replaced by a bond stack — signals that the European credit market has sufficient depth to finance a "single B" at this scale without relying on a single lead bank. For an industrial acquirer or a sovereign fund monitoring the European specialized pharma market, the signal is twofold: liquidity exists for defensive assets, and the delisting of a player of this size mechanically reduces the pool of available listed targets.
📰Today's news · 00 evaluable in the cockpit
Vestbee — overview of European fundraisings in October 2026: robotics and defense lead the way
This entry is a monthly digest compiled by Vestbee listing fundraisings closed in October 2026 across Europe. Several operations are described with precise amounts and named companies.
MACHENTA (London, 2025), a robotics startup, raised $40 million in seed funding from Union Square Ventures and Creandum to develop an AI model enabling robots to learn new tasks from a single demonstration.
Braid (London, 2023), a connectivity technology company for businesses, raised $38 million in Series A funding from Octopus Ventures and KPN Ventures to develop its embedded connectivity infrastructure and telecom operator network.
Duvo (Altrincham, 2025), an AI startup offering an execution platform for retail and consumer goods companies, raised $32 million in Series A funding from Index Ventures, Balderton Capital, Northzone, Credo Ventures, and Puzzle Ventures to expand into the US market.
Beyond Vision (Lisbon, 2013), a drone system manufacturer, raised over €28 million co-led by Índico Capital Partners and Lince Capital to develop its industrial production, AI and drone swarm technologies, and expand its international presence in defense and critical infrastructure.
Enact Intelligence (Zurich, 2026), a robotics startup developing force sensing technologies to improve robot object manipulation, raised $30 million in pre-seed funding from redalpine, Notion Capital, Firstminute Capital, Thomas Wolf, and Arthur Mensch.
Phononic Vibes (Milan, 2018) raised €25 million from CDP Venture Capital, 360 Capital, Jolt Capital, and SkyDeck Berkeley (the rest of the source text is truncated).
This October overview confirms a trend already visible in November: robotics and defense are attracting the highest tickets at early stages, with transatlantic investors present from seed — a sign that these sectors are now treated as strategic priorities, not just as return opportunities.
📩 Subscribe to our newsletter to follow daily M&A and fundraising news: https://proplace.co/newsletter
📰Other news today — no identifiable company · 16outside the cockpit — explore via 🔎
- Vivify acquires imin: connecting school sports facilities to booking platformsbusinesscloud.co.uk
- Advent appoints Mal McHutchison as an Operating Partner ...adventinternational.com
- In Extenso nomme deux nouveaux associés en région ...laprofessioncomptable.com
- Le groupe Adelaïde annonce la nomination de Sylvain ...mediadreams.fr
- Apollo lance un fonds de dette privée de 10 milliards en ...latribune.fr
- Annonce d'accords de licence et d'approvisionnement pour ...prnewswire.com
- Startup | Top 84 des Levées de Fonds en France en 2026independant.io
- La BEI lève 10 Md€ pour investir dans les champions européenstelegraaf.nl
- Le gouvernement néerlandais investit 200 M€ dans les startups européennesemerce.nl
- Les levées de fonds de la semaine (S45 2026)multeam.substack.com
- Mapping 2026 des startups françaises à impact 1 382 ...presse.bpifrance.fr
- Top VCs & Startup Programs in Austria (2026)incubatorlist.com
- Qui couvre la tech en France ? La carte des médias techlinker-agency.com
- Mesh, levier financier au services des startupslyon-metropole.cci.fr
- Diagnostic messaging B2B : votre site noté en 10 minutes.fast-growth.fr
- Mastères Spécialisés - MINES PARISminesparis.psl.eu
Set aside today · 321 (with reason)
- Girtz Industries — already covered
- CCI — incomplete M&A — buyer or target not identified
- Usine de Brampton — out of scope
- Site Wyoming — hors_europe
- Palatal — hors_europe
- AQQI — already covered
- Bleu Robotics — already covered
- Ridero — already covered
- Vodafone Italia — already covered
- TIC acquisitions — incomplete M&A — buyer or target not identified
- Italian Banking M&A — incomplete M&A — buyer or target not identified
- The Rapid Group — already covered
- OneX Intelligence — hors_europe
- Firmly — pays_non_etabli
- VCs — already covered
- CEE — already covered
- Vaeridion — already covered
- ACC-M — incomplete M&A — buyer or target not identified
- CFNEWS — out of scope
- CGP — incomplete M&A — buyer or target not identified
- RAISE — already covered
- Echodyne — hors_europe
- Pigment — already covered
- Actu Fusions-Acquisitions — incomplete M&A — buyer or target not identified
- IA — already covered
- Millenium Associates — incomplete M&A — buyer or target not identified
- Strategy — incomplete M&A — buyer or target not identified
- Laprophan — incomplete M&A — buyer or target not identified
- SkipLabs — already covered
- Ilva — incomplete M&A — buyer or target not identified
- WhatsApp appartient à Meta — incomplete M&A — buyer or target not identified
- Flora — hors_europe
- Growth Co Marketing — hors_europe
- Enercare — hors_europe
- Pillar — hors_europe
- Nominal — hors_europe
- Venomics AI — already covered
- MENA — pays_non_etabli
- enza — hors_europe
- Avanlee Care — hors_europe