Analysis of M&A and Fundraising Operations on November 22, 2026
European logistics undergoes major restructuring, industrial AI attracts telecoms, and France consolidates its management tools — today's movements deciphered for decision-makers and investors.
· Proplace
🌡️ Sectors on the move — hover a sector to see its deals, click to open it
Open this edition in the cockpit →Every deal of the day, unfolded, evaluable in one click.
The day is driven by two distinct dynamics that, while not directly related, are complementary: on one hand, heavy industrial consolidations in logistics, infrastructure, and engineering; on the other, bets on the software layer — accounting, AI, green mobility — where value is now less about assets and more about the customer base. France, in the background, continues to quietly accumulate capital in its startups at a rate that warrants attention.
🤝Signed-deals stream · 88 evaluable in the cockpit
- InPost
FedEx and InPost: When an American Giant Buys Eastern Europe's Nervous Infrastructure
FedEx and InPost: When an American Giant Buys Eastern Europe's Nervous Infrastructure
Source: ground.news → · Sector Mobility & Transportation — 📬 subscribe to the Mobility & Transportation newsletter
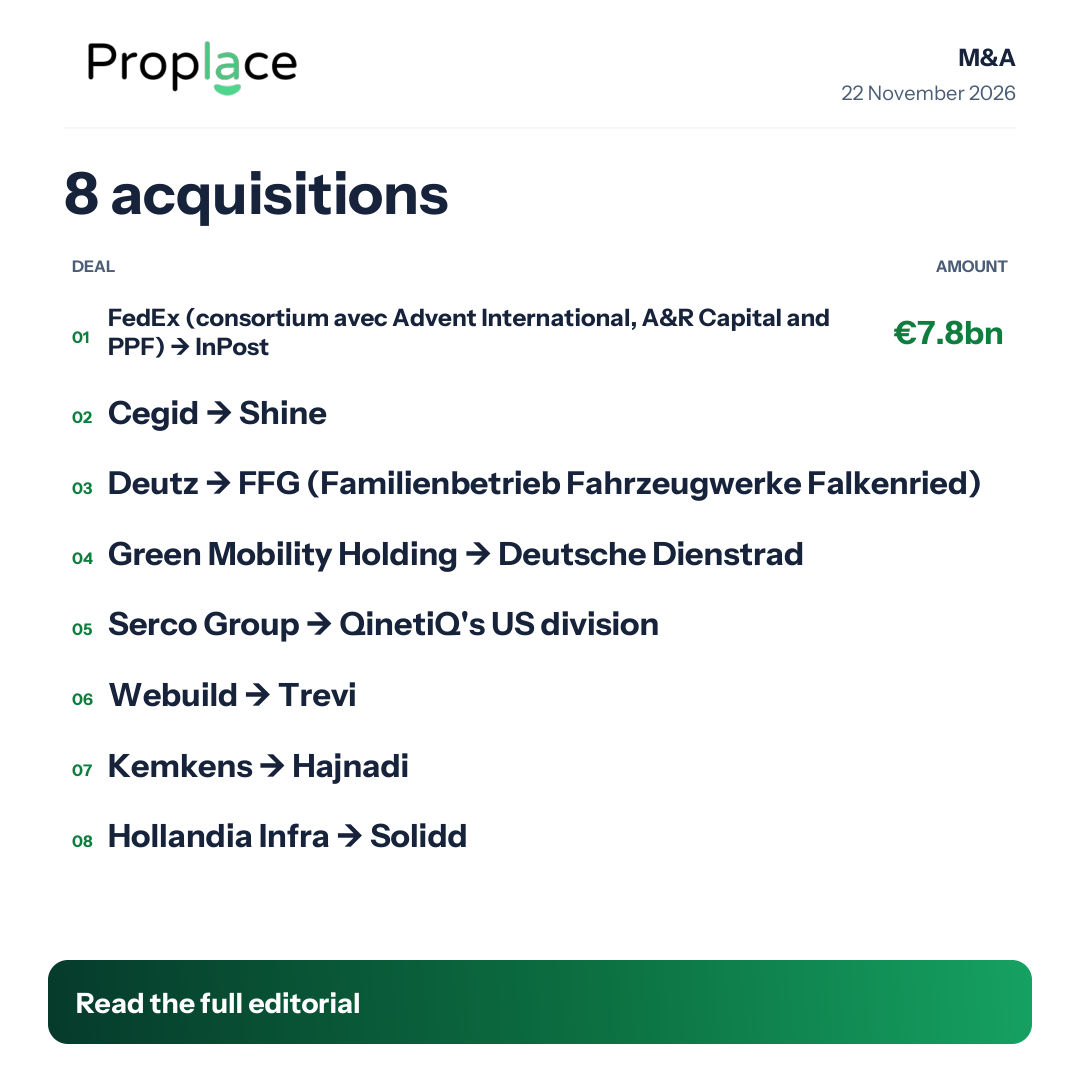
InPost is the dominant network of automated parcel lockers and delivery services in Poland, with a growing presence in France, the UK, and several Western European markets. Its model relies on large-scale physical lockers — an infrastructure that end-customers adopt out of habit, and that e-commerce can no longer ignore. A consortium led by FedEx, alongside Advent International, A&R Capital, and PPF, finalized its acquisition for €7.8 billion, concluding a process initiated in February.
The obvious interpretation: FedEx closes its structural gap in Europe, where UPS and DHL have long had capillary networks, by acquiring in one fell swoop the player that reinvented last-mile delivery without a heavy fleet.
What is less discussed: InPost is not a delivery company in the classic sense — it's an access infrastructure, a network of physical points that merchants integrate into their sales funnels. FedEx is not buying additional trucks or warehouses; it is buying the direct relationship with tens of millions of European consumers who have already changed their behavior. The real execution question will be whether FedEx knows how to operate a proximity network based on density and habit — a model radically different from the long-distance B2B logistics that is its core business.
- Shine
Cegid Acquires Shine: Management Software for Freelancers Falls into Line
Cegid Acquires Shine: Management Software for Freelancers Falls into Line
Cegid is a French publisher of management software (accounting, payroll, tax) historically rooted in accounting firms and SMEs. Shine — formerly Ageras in France — is a professional neobank and financial management tool for freelancers, micro-entrepreneurs, and very small businesses: it has 420,000 clients, employs 400 people, and generates €100 million in revenue. This is Cegid's second acquisition in 2026.
Obvious interpretation: Cegid extends its reach downmarket, where freelancers and very small structures did not yet have an integrated solution within its ecosystem.
The deeper movement is that of a platform closing its loop. Cegid serves accountants; accountants serve their VSB/freelancer clients; Shine serves these same clients directly. By acquiring Shine, Cegid is not just growing — it is potentially short-circuiting the intermediary or, conversely, offering them an additional tool to propose. With 420,000 active clients already acquired, the real value is not in the revenue: it is in the behavioral database of a rapidly growing population of independent workers, which no one else in the Cegid portfolio had reached until now.
- FFG (Familienbetrieb Fahrzeugwerke Falkenried)it-boltwise.de
Deutz Acquires FFG: Engine Power Seeks Its Return
- Deutsche Dienstradvelodisco.com
Deutsche Dienstrad Joins Green Mobility Holding: Soft Mobility Takes Shape
- QinetiQ's US division
Serco Acquires QinetiQ's US Division: Defense Services Look Across the Atlantic
- Trevi
Webuild Acquires Trevi: Italian Heavy Engineering Consolidates
Webuild Acquires Trevi: Italian Heavy Engineering Consolidates
Webuild is an Italian construction and civil engineering group, active in major infrastructure projects (tunnels, dams, metros, water). Trevi is an Italian specialist in special foundations and geotechnical works (injections, diaphragm walls, soil consolidation). Webuild is taking control, with the amount undisclosed.
Strategic interpretation: Special foundations are the invisible but critical link in any major infrastructure project — without them, no tunnel or bridge stands. By integrating Trevi, Webuild internalizes a competence it probably subcontracted, reducing its dependence on suppliers for its own projects and strengthening its ability to bid alone on complex projects.
- Hajnadi
Kemkens Takes Over Hajnadi and Knibbeler: Dutch Technical Installation Consolidates
Kemkens Takes Over Hajnadi and Knibbeler: Dutch Technical Installation Consolidates
Kemkens is a Dutch technical installer (HVAC, electrical, plumbing). It is taking over Hajnadi and Knibbeler, two companies in the same sector in the Netherlands. Amount undisclosed. A sectoral consolidation operation in a fragmented technical installation market.
- Solidd
Hollandia Infra Acquires Solidd: Structural Steel Changes Hands in Friesland
Hollandia Infra Acquires Solidd: Structural Steel Changes Hands in Friesland
Hollandia Infra is a Dutch player in metal construction and infrastructure. It is taking over Solidd, a steel constructor based in Sumar (Friesland, Netherlands). Amount undisclosed. A geographical build-up operation in industrial metal construction.
Deutz Acquires FFG: Engine Power Seeks Its Return
Deutz is a German engine manufacturer specializing in industrial engines (construction machinery, agriculture, energy). FFG (Familienbetrieb Fahrzeugwerke Falkenried) is a manufacturer and reconditioner of industrial vehicles. Deutz has finalized the acquisition of FFG, with the stated rationale focusing on new incoming contracts — but according to sources, the share of profits will be decisive in judging the success of the operation.
Hypothesis: In an engine sector under pressure from the energy transition, Deutz seeks to diversify its outlets downstream — fleet maintenance and conversion — rather than remaining solely exposed to demand for new engines. FFG could represent access to recurring revenue cycles (maintenance, retrofit) that are less volatile than the sale of powertrains.
Serco Acquires QinetiQ's US Division: Defense Services Look Across the Atlantic
Serco Group is a London-listed government services provider (defense, health, transport, justice). QinetiQ is a British defense and technology group, spun out of the UK Ministry of Defence's research laboratory. Serco has agreed to acquire QinetiQ's US division, with the amount undisclosed.
Strategic interpretation: For a British government services provider, access to the US defense market is structurally difficult — US federal contracts favor US-domiciled entities. Acquiring an entity already established and accredited in the United States is the shortest path to access this market without starting from scratch.
Deutsche Telekom Bets €100 Million on Mistral to Enter German Industry
Mistral AI is a French company developing large language models, positioned as a European alternative to American models (OpenAI, Anthropic) and distributing its models open-weight and via API. Deutsche Telekom is investing €100 million in Mistral with an explicit objective: to deploy Mistral's models in German industry, a fabric of SMEs and Mittelstand that forms the country's economic backbone.
Obvious interpretation: a major telecommunications company invests in AI to reposition itself as an integrator, beyond mere connectivity.
What is strategically interesting is the choice of partner. Deutsche Telekom could have — like other operators — partnered with a licensed American model. By taking a stake in Mistral, it gains a position in the governance of a player of which it will become one of the main industrial distribution channels in Europe. For Mistral, the stakes are symmetrical: Deutsche Telekom is a direct gateway to thousands of German industrial companies that do not have the teams to integrate an API themselves, but who trust their historical operator. This is less a financial investment than a distribution agreement disguised as a funding round.
💰Fresh-funding radar · 11 evaluable in the cockpit
- Mistral AIfrenchweb.fr
Deutsche Telekom Bets €100 Million on Mistral to Enter German Industry
Deutsche Dienstrad Joins Green Mobility Holding: Soft Mobility Takes Shape
Source: frenchweb.fr → · Sector Industrial Tech & Manufacturing — 📬 subscribe to the Industrial Tech & Manufacturing newsletter
Deutsche Dienstrad is a German operator of company bicycles (leasing bicycles for employees via the employer), a market that has grown significantly in Germany due to tax advantages. Green Mobility Holding is acquiring it, with the amount undisclosed. No additional details on the holding's strategy or targeted synergies are available in the sources.
📰Today's news · 44 evaluable in the cockpit
- France startup funding 2026 to datefunding.tech.eu
France startup funding 2026 to date: €8.9B equity
- Mistralfrenchweb.fr
Deutsche Telekom investit 100 millions d'euros dans Mistral pour l'industrie allemande
- GENESIS AIlefilia.fr
GENESIS AI renforce la robotique humanoïde industrielle française
- Aricomaaroundprague.cz
Milan Sameš of Czech IT group Aricoma: buyouts and McLaren
France at €8.9 Billion: Capital Accumulates, the Question is Depth
The cumulative 2026 fundraising for French startups reached €8.9 billion in equity across 224 rounds completed by 212 companies, with an additional €2.1 billion in debt. This aggregated figure, published by Tech.eu, is a snapshot of the entire ecosystem since January.
What deserves attention in this figure is not the raw volume, but the concentration it likely conceals. Large venture capital markets operate under a power law: a few mega-rounds capture the majority of the total amount, while the median round remains modest. The past week is a direct illustration of this — Genesis AI at €455 million alone represents a significant portion of the week's €526 million. For a French investor or executive, the real question is not the total: it is whether the remaining 200 rounds are funding companies capable of generating returns, or if most of the capital is concentrated on a handful of very high-tech bets.
📰Other news today — no identifiable company · 19outside the cockpit — explore via 🔎
- William Blair Expands European Team with Appointment of ...themiddlemarket.com
- GIC appoints new CIO for private equitypei-secondariesinvestor.com
- OGO Security nomme Nicolas Van Den Torren directeur ...mediadreams.fr
- KPMG France nomme trois associés à la tête de l'Audit et ...compta-online.com
- Sinch Appoints Jonas Dahlberg as CEOreaditquik.com
- Rothschild & Co appoints Geoffory De Ridder as group ...fintechfutures.com
- Levées de fonds de la French Tech : chiffres et tendancesintotheminds.com
- Orange engage 250 millions d'euros pour financer les ...af.net
- Levées de fonds de la semaine 46 🇫🇷anti-dealflow.com
- LES LEVEES DE FONDS DES STARTUPS DE LA FRENCHTECHfrenchweb.fr
- Tories and universities raise concerns over Burnham’s Brussels dealtimes-series.co.uk
- Pivotal Ventures Expands Into Private Equity For Women's ...forbes.com
- DP World Tour: Rolex Series and Ryder Cup Racepeoriaridge.com
- Levées de fonds startups françaisesuclic.fr
- M&A, restructuration et levées de fonds France-Marocvillage-justice.com
- Conseils M&A en Suisserepertoire.finance
- Analyste Junior Corporate Finance M&A - Paris - 2027 H/Fjobteaser.com
- Agence de branding pour startups à Genèvestartupbrander.com
- Dermatose nodulaire, Mercosur : les agriculteurs mobiliséstf1info.fr
Set aside today · 302 (with reason)
- Avio — already covered on il y a 4 j
- Services — incomplete M&A — buyer or target not identified
- BPA — incomplete M&A — buyer or target not identified
- MSP — pays_non_etabli
- Insmed — already covered
- Model ML — pays_non_etabli
- Genesis AI — already covered on il y a 11
- Variational — hors_europe
- Speeral — already covered
- Humyn Labs — hors_europe
- Previsia — already covered
- Everful — already covered
- Commerzbank — already covered on 5 days ago
- ArcelorMittal CLN Distribuzione Italia — already covered
- LP — pays_non_etabli
- The Rapid Group — hors_europe
- Fractile — already covered
- STMicroelectronics — out of scope
- Atomico — already covered
- INVE — hors_europe
- KIKA AI — pays_non_etabli
- Plural — already covered
- Iconic — already covered
- STEVE — out of scope
- OVHcloud — out of scope
- IA — out of scope
- Brakebush — hors_europe
- IAEA — incomplete M&A — buyer or target not identified
- Isomorphic Labs — already covered on il y a 4 j
- Nector — out of scope
- Exemple de dossier de levée de fonds — pays_non_etabli
- Namkin — already covered
- triPica — already covered
- Zscaler — hors_europe
- Mailchimp — already covered on 2026-11-21
- Kira Talent — hors_europe
- Bill — hors_europe
- C1 Connections — already covered
- Murnane — incomplete M&A — buyer or target not identified
- Mindler — hors_europe